What a gram costs here, against the world
Gold is priced internationally in dollars, but India buys it in rupees. The two prices never meet on the same page, so the gap between them is easy to miss. This site converts both to one gram and shows the difference, before tax and after.
Compare the Indian benchmark gram against the international gram, both in rupees, and see what sits between them.
Import duty, landing cost, domestic premium and tax each take a slice, and some move from week to week.
The international price is a wholesale quote for metal abroad, not a price you can buy at, and the premium is not a saving you can capture.
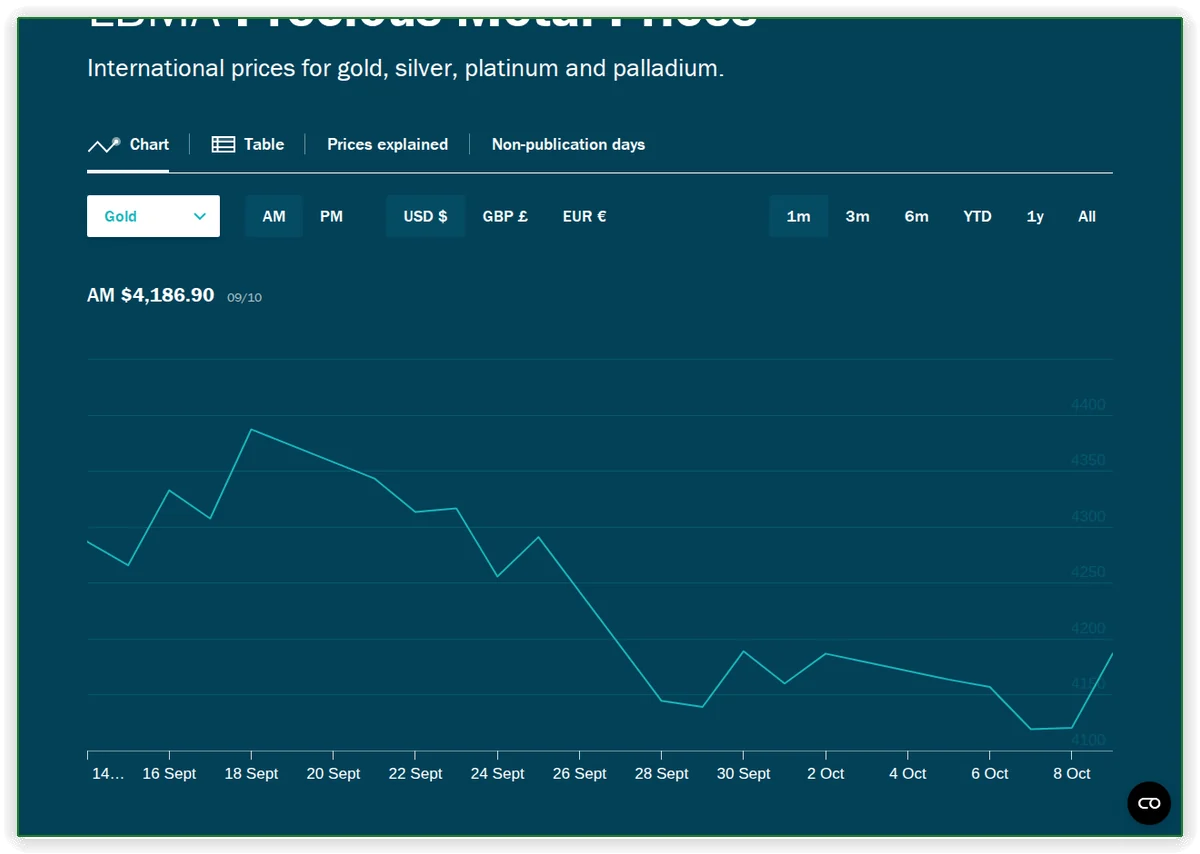
The same gram, here and abroad
Both prices read: 09.11.2026 18:30| The same gram | In India | International | Difference | Premium |
|---|---|---|---|---|
| Gold 999, before tax | ₹14,145.20 | ₹12,450.71 | ₹1,694.49 | +13.61% |
| Gold 999, with GST | ₹14,569.56 | ₹12,450.71 | ₹2,118.85 | +17.02% |
| Gold 916, with GST | ₹13,345.71 | ₹11,404.85 | ₹1,940.86 | +17.02% |
The domestic rate is the association's own; the international price comes from two independent sources and is converted to rupees a gram.
Domestic benchmark as published by the India Bullion and Jewellers Association (IBJA)
What you will learn
The gap itself
How the Indian gram compares to the international gram once both are in the same unit, and why that comparison matters.
02What the gap is made of
The components inside the difference: import duty, landing cost, domestic premium and tax, and which ones change from week to week.
03The rupee in the price
How the exchange rate moves a rupee gold price, and how to tell whether the dollar or the rupee moved on a given day.
04Why shops differ
Why two shops in the same city quote differently despite one national benchmark, and what part is the shop rather than the metal.
05What this is not
The limits of the comparison: an international price is wholesale, and the premium measured here is not a saving anyone can capture.
The premium is already embedded in every rupee quote before you see it
When a jeweller quotes a rate for a gram of gold, that number is not the international price converted at the day's exchange rate. It already carries the import duty, the landing charges and the domestic premium inside it. By the time the quote reaches a screen or a shop board, the gap has been built in. A buyer who only compares rupee quotes across two shops is comparing two versions of the same loaded price.
The domestic benchmark published by bullion associations is itself a composite. It takes the international spot, converts it at a reference rupee rate, then adds the duty and an average premium observed in the wholesale market. That benchmark is the base for retail quotes, but it is not the price at which metal actually changes hands in every city on that day.
Because the premium is embedded before the quote is made, a fall in the international dollar price does not automatically show up as an equal fall in the rupee quote. The rupee may have moved, the domestic premium may have widened on local demand, or dealers may be holding inventory bought at a higher landed cost. The visible quote is the end of a chain, not a transparent window on the world price.
The premium is paid on every purchase, but refunded on almost none
When a buyer purchases gold, the premium is part of the outlay. Import duty, landing costs, the domestic premium and the tax are all paid at the time of purchase. None of these components are returned when the gold is sold back to a jeweller or a refinery. The buy-back price is based on the prevailing benchmark, which may or may not include the full premium that was paid earlier.
A jeweller buying back old gold typically pays the day's benchmark rate minus a refining margin. That benchmark already includes the current import duty and domestic premium, but it is a wholesale rate. The seller does not get back the making charges paid originally, nor the tax paid on the final invoice. The premium paid at purchase is sunk.
This asymmetry means that the premium works like a transaction cost that is charged on entry and not returned on exit. The longer the holding period, the less the premium matters as a fraction of total return, but it never comes back. A buyer who sells soon after purchase realises the full premium as a loss unless the underlying metal price has risen enough to cover it.
The premium can widen while the world price falls, and vice versa
The domestic premium is not a fixed markup. It responds to local supply and demand, to the availability of imported metal, to festival-season buying and to credit conditions among bullion dealers. When local demand is strong and imports are delayed, the premium can rise even as the international dollar price is falling. A buyer in India may see a rupee price that is flat or only slightly lower while the world price has dropped sharply.
Conversely, when local demand is weak or when dealers have built up large inventories, the premium can compress. The rupee price may then underperform the international price on the upside. A rise in the dollar price may be partly offset by a shrinking premium, so the rupee quote does not move up as much as the conversion alone would suggest.
Because the premium is a market price in its own right, it can move independently of the metal price and the exchange rate. This is why a single day's gap between the Indian rupee quote and the converted world price is not a stable number. It is the sum of a policy layer and a sentiment layer, and the sentiment layer can turn quickly.
The tax on gold is charged on a base that already includes the premium
The goods and services tax on gold is calculated on the final invoice value, which includes the metal price, the import duty, the landing charges and the domestic premium. This means the tax is levied on a base that has already been inflated by the very gap this site measures. The tax does not create the premium, but it magnifies it.
Because the tax is a percentage of the total, a wider premium automatically produces a larger tax amount per gram. The buyer pays tax on the premium and on the duty, not just on the underlying metal value. This compounding effect is rarely visible on a shop invoice, which shows one tax line against a total that has already absorbed all the earlier layers.
The effective tax rate on the pure metal value is therefore higher than the statutory rate. A buyer who compares the Indian landed cost before tax with the final price after tax can see how much of the final outlay is tax charged on top of a premium that was itself added inside the country. The tax is the last layer, but it is applied to the whole stack.
A loan against gold is marked to a benchmark that may ignore what you paid
When gold is pledged as collateral for a loan, the lender values the metal at the prevailing benchmark rate, not at the price the borrower paid. If the borrower bought at a time when the domestic premium was unusually high, the loan amount will be based on a lower current benchmark, and the premium paid at purchase is not recovered in the loan valuation.
The loan-to-value ratio is applied to the benchmark, which includes the current import duty and domestic premium but not the historical premium paid by the borrower. A wide premium at the time of purchase therefore reduces the effective loan amount relative to the total outlay. The borrower has paid more per gram than the lender will recognise as collateral value.
Moreover, if the domestic premium narrows after the loan is taken, the benchmark value of the pledged gold falls even if the dollar metal price and the rupee exchange rate are unchanged. The borrower may face a margin call or a lower renewal amount purely because the premium compressed. The premium is thus a risk factor in gold-backed lending.
Buying gold in a low-premium city is not the same as buying it cheap
The domestic premium can differ across cities and even across dealers within a city. A buyer who travels to a market known for lower premiums may pay less per gram than at home, but the difference is often small relative to the total cost. The saving on the premium can be offset by travel costs, by the risk of carrying metal, or by a higher making charge in that market.
Moreover, a low premium in one city may reflect weaker local demand or a surplus of inventory, not a better price for the buyer. The metal is the same, but the transaction environment differs. A buyer who chases a lower premium without considering the full invoice may end up paying more once making charges and tax are added.
The premium is only one part of the final price. A comparison that focuses on the premium alone can mislead. The same purity and weight of metal can carry different making charges, different tax treatment depending on the form of purchase, and different buy-back terms. A low premium does not automatically mean a better deal.
The exchange rate used in the conversion is not the rate you can get
The international dollar price is converted to rupees using a reference rate, often the Reserve Bank's published rate or a market rate at a specific time. But a retail buyer cannot buy dollars at that rate. The rate at which one actually acquires foreign exchange, whether for travel or for import, includes a bank's margin and may differ from the reference rate by a noticeable spread.
For a bullion importer, the cost of dollars is not the same as the interbank rate. Banks charge a spread on the conversion, and the importer may also pay hedging costs if the currency exposure is covered. These costs enter the landed price of gold but are not separately visible on a shop invoice. They are part of the landing charges or the domestic premium.
Thus, when this site converts the international price to rupees, it uses a benchmark exchange rate that is clean and observable. The actual rate paid by the importer is slightly worse. That difference is another small layer inside the premium, one that is rarely disclosed but is always present.
The premium is different for coins, bars and jewellery, even for the same purity
The domestic premium on gold is not uniform across all forms. Coins and bars usually carry a lower premium than jewellery because they are closer to bullion and have minimal making charges. Jewellery carries an additional making charge that is not part of the premium but is added on top of it. A buyer comparing the premium on a coin with the premium embedded in a jewellery price is not comparing like with like.
Within jewellery, the premium on the metal is the same for a plain bangle and an intricate necklace, but the making charge differs enormously. The total price per gram for the necklace will be higher, yet the premium component is the same. A buyer who attributes the entire difference to the premium misunderstands the price structure.
The tax treatment can also differ. Investment-grade coins and bars may attract a different tax rate or different documentation requirements than jewellery. These differences mean that the effective premium per gram, measured as the total price over the international converted price, varies by product even when the underlying metal premium is identical.
Open an account with FxPro
FxPro quotes gold as a contract for difference. No metal is delivered and none is stored. The account is settled in the currency you choose, and opening one requires identification and takes a day or two.